Helping a wide range of borrowers
Wages, salaries, painters, builders, electricians, plumbers, business owners - helping you find lending solutions that best suit your circumstances.
Based in Christchurch and serving clients across Canterbury and NZ, our mortgage broker understands how lenders assess self-employed income. With 17 years of banking experience on both sides of the desk, we know how to present self-employed home loan applications in the strongest possible light, whether you’re a contractor, freelancer, sole trader or small business owner.
We work with 30 lenders
Not every lender treats self-employed borrowers the same. Different lenders have different lending policies. We help identify lenders whose criteria may best suit your circumstances.
We consider your financial circumstances, goals, objectives and preferences before recommending a lender or loan structure. Recommendations are based on suitability for your individual situation and not simply on lender availability.
How much does a
mortgage broker cost?
In more complex cases, a fee may apply. If that's the case for you, we'll tell you what it is and why before we do any work, so there are no surprises.
Full details of our fees, commissions and any conflicts of interest are set out in our disclosure documents, which we provide before giving you advice.
Mortgage solutions
for self-employed Kiwis
Self-employed home loans
First home buyers
Pre-approvals & borrowing power
Refinancing & better rates
Supporting services for business owners
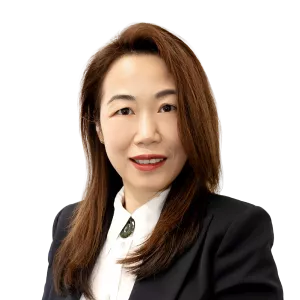
Vivien Qin
MBA University of Canterbury
Having worked across some of New Zealand's most respected lenders, she knows exactly how banks think, what they're looking for, and how they assess self-employed borrowers. It's a perspective few advisers can offer, and one that makes a real difference when your income doesn't fit neatly into a standard box.
Her background as a business manager, relationship manager, and asset finance specialist across the South Island gives Vivien a deep understanding of business income in all its forms, whether you're a contractor, sole trader, or company director. She's equally experienced helping wage and salary earners find the right fit.
Vivien also holds an MBA, giving her a strong understanding of how businesses operate and run. Based in Christchurch, she works with clients across Canterbury and throughout New Zealand to find a lending solution that fits the way you actually earn.
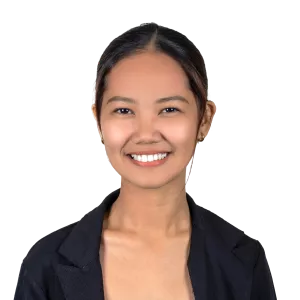
Antonette Escorial
Backed by a Bachelor of Science in Management Accounting and hands-on experience across multiple loan sectors, Antonett brings a highly analytical edge to the lending process. Her accounting background gives her a deep understanding of complex financial profiles and cash flows, skills that are invaluable when packaging applications and negotiating with lenders.
Having worked across a wide variety of loan types, she draws on this combined expertise to analyse her clients' financials, anticipate potential roadblocks, and deliver solutions that protect their bottom line.
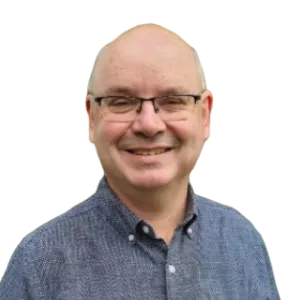
Peter MacGibbon
He brings clarity and calm oversight to financial and property matters, drawing on strong experience in construction, compliance, and project risk. Deeply connected to his community, Peter focuses on responsible development and thoughtful governance that support families, strengthen local organisations, and contribute to a resilient, well-planned Christchurch.
Steps to getting your home loan
1
Free consult
2
Your mortgage options
3
Start house hunting
4
Set up your loan
Frequently Asked Questions
Most major New Zealand banks want to see at least two years of steady business history. They need to know that your earnings from last year weren't just luck and that you can keep making enough money to repay a mortgage. That said, two years is not an absolute rule, the type of business matters. A contractor with a consistent client and predictable income may be assessed more favourably than a new café owner with variable earnings.
Yes, in some cases. Most New Zealand banks want to see two years of trading history. But with only one year of records, you may still qualify, particularly if you have solid prior experience in the same field and strong earnings in your first year of business. Non-bank lenders tend to be more flexible. Some will consider applications from borrowers who have been self-employed for as little as six months, using alternative documentation such as six months of business bank statements. Your deposit also plays a significant role: a larger deposit gives lenders more comfort and opens up more options. Every situation is different, so it's worth talking it through. Get in touch and we'll look at what's achievable for you.
You'll need your last two years of financial statements (Profit & Loss and Balance Sheet) and the matching IRD Summary of Earnings or tax assessments. Banks also want to see your recent business bank statements to check for steady cash flow. If your most recent tax year ended recently, they might also ask for interim management accounts to show how your business is performing now. Having your accounts on software like Xero or MYOB makes this process significantly faster and cheaper.
Yes. KiwiSaver first home withdrawal rules apply equally to self-employed members. The key difference is that if you're self-employed, working as a contractor, freelancer or sole trader and not receiving PAYE income, some of the benefits of employment are not available, such as having your employer make contributions. You need to make your own contributions directly. If you contribute at least $1,042.86 before 30 June each year, you'll receive the maximum government contribution of $260.72.
Yes, but not unfairly. Banks want to lend to successful business owners. They just need more convincing than they do with PAYE employees, who can show a couple of payslips. The key difference is income verification. If you're self-employed, the bank bases your mortgage on your taxable profit, not what you pay yourself. This means careful tax planning that minimises your declared income can work against you at mortgage application time.
What our Clients say
Request your free consultation
Monday – Friday: 9am-6pm
Saturday: 10am-12pm